Container Glass Market Overview
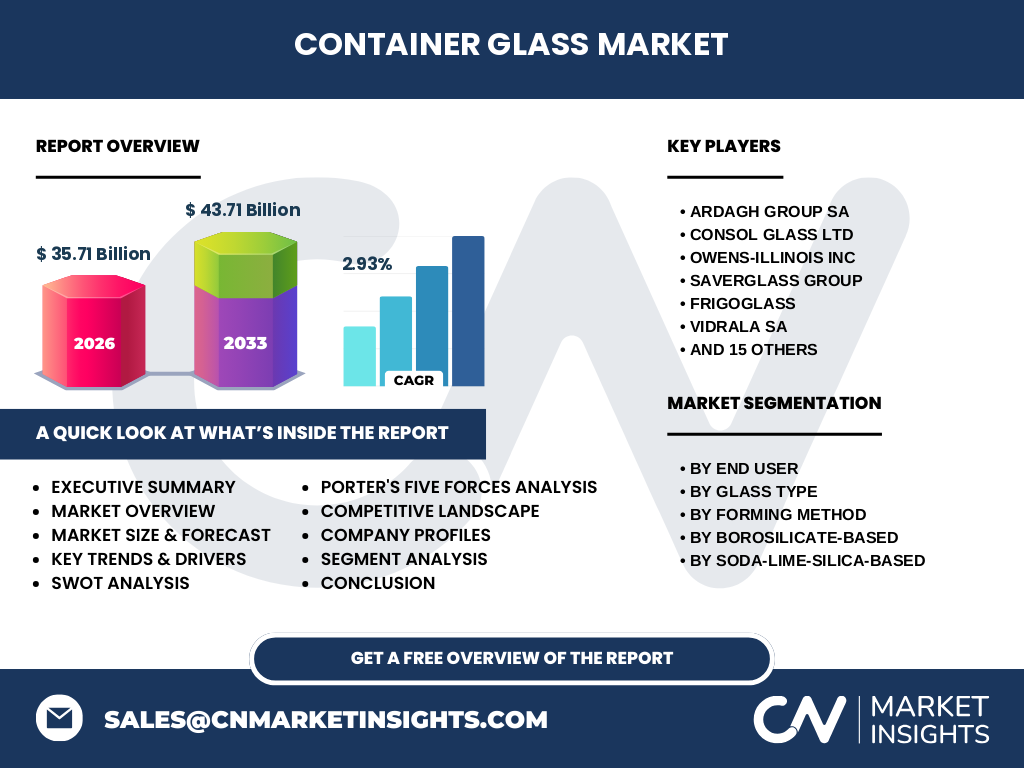
The Container Glass Market represents a vital industrial segment encompassing rigid packaging solutions manufactured from silica, soda ash, and limestone. Valued at $35.71 Billion in 2026, this sector underpins the global supply chain for premium food, beverage, and pharmaceutical preservation, offering unmatched chemical inertness and infinite recyclability compared to polymer alternatives.
Structural Growth Drivers and Restraints in the Container Glass Market
Our analysis indicates that consumer preference for premium, sustainable packaging fuels the Container Glass Market industry trends. However, high energy intensity required for furnace operations and volatile soda ash pricing act as primary restraints. Growth opportunities lie in lightweighting technologies pioneered by market leaders to mitigate freight cost pressures.
Emerging Trends and Growth Patterns in Container Glass Market
The transition toward PCR (post-consumer recycled) glass integration dominates current Container Glass Market analysis. Eco-conscious brand positioning by beverage conglomerates accelerates demand for amber and flint glass variants that maintain high aesthetic standards while lowering carbon footprints during the melting phase.
COVID-19 Impact Analysis on the Container Glass Market
The pandemic caused severe supply chain disruptions across the Container Glass Market, particularly regarding raw material logistics and furnace maintenance delays. Yet, resilient demand from pharmaceutical packaging and off-premise beverage consumption cushioned the sector, facilitating a robust recovery trajectory heading toward our forecast period.
Competitive Benchmarking in the Container Glass Market
Market concentration remains moderately high, with major multinational players like Owens-Illinois Inc., Ardagh Group SA, and Verallia dominating global volume. Strategic consolidation and regional footprint expansions allow these incumbents to secure long-term supply contracts with multinational beverage and pharmaceutical giants.
Executive Summary of the Container Glass Market
Our comprehensive Container Glass Market report overview projects the sector to reach $43.71 Billion by 2033, expanding at a steady 2.93% CAGR from 2027. Sustainability mandates and premiumization are reshaping operational strategies across soda-lime and borosilicate manufacturing facilities worldwide.
Container Glass Market Forecast (2027 to 2033)
Driven by compounding demand in emerging economies and stringent anti-plastic regulations, the Container Glass Market market size is set for sustained upward momentum. We project steady incremental gains, culminating in a total market valuation of $43.71 Billion by the end of 2033.
Segmentation Analysis of the Container Glass Market
The Container Glass Market is segmented by end-user into Food And Beverages, Cosmetics And Personal Care, Pharmaceuticals, Chemical, and Other End-Users. Glass types divide into Borosilicate-Based (Laboratory Glassware, Food And Beverage Containers, Pharmaceutical Packaging) and Soda-Lime-Silica-Based (Food And Beverage Bottles, Jars And Jugs, Pharmaceutical Containers). Forming methods include Blow And Blow, Press And Blow, and Narrow Neck Press And Blow.
Regional Market Analysis and Geographic Distribution
Geographic performance within the Container Glass Market varies significantly based on local regulatory frameworks and beverage consumption habits. Europe commands a substantial share due to strict environmental mandates, while Asia-Pacific represents the fastest-growing region driven by surging urbanization and expanding middle-class disposable incomes.
In-Depth Regional Review
Regional dynamics reflect localized supply constraints and energy cost differentials. European producers face stringent carbon taxation, pushing investments into hybrid electric-gas furnaces. Meanwhile, North American operations focus on high-speed automated lines to serve massive domestic soft drink and craft brewing distribution networks.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct competitive strategies within the Container Glass Market. Companies like Vidrala SA and Vetropack Group emphasize localized manufacturing proximity to reduce freight emissions, whereas specialized players like Saverglass Group capture high-end spirits segments through bespoke aesthetic designs.
Porter's Five Forces Analysis of the Container Glass Market
Rivalry within the Container Glass Market is intense due to high capital expenditure requirements for furnace assets. Supplier power remains moderate concerning high-grade silica sand, while buyer power is high among multinational beverage conglomerates capable of negotiating volume-based pricing terms.
SWOT Analysis for Industry Stakeholders
Strengths include infinite recyclability and superior chemical barrier properties. Weaknesses stem from high transportation costs due to product weight. Opportunities reside in lightweighting innovations, whereas threats involve aggressive substitution by lightweight aluminium cans and advanced polymer packaging formats.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with the extraction of raw silica sand, soda ash, and limestone, progressing through high-temperature batch melting in regenerative furnaces. Forming machines shape the molten glass before annealing lehrs relieve internal stresses, culminating in distribution to end-users like Gerresheimer AG and Hindusthan National Glass & Industries Ltd.
Investment Insights and High-Potential Areas
Investors should target technological innovations focused on decarbonization, specifically hydrogen-fueled furnaces and advanced optical sorting systems for cullet recycling. High-potential growth is concentrated in pharmaceutical-grade borosilicate containers and premium cosmetic glass packaging.
Conclusion and Key Takeaways
The Container Glass Market exhibits resilient long-term fundamentals anchored by sustainability trends and regulatory headwinds against plastics. Achieving a 2.93% CAGR through 2033 underscores the sector's ability to modernize traditional manufacturing processes to meet modern ecological demands.
Research Methodology
Our baseline estimates for the Container Glass Market are triangulated using a rigorous methodology combining trade registry data, primary stakeholder interviews with executives from O-I Glass Inc. and Stoelzle Glass Group, and secondary macroeconomic indicators regarding glass container production volumes.
Scope of the Report
This report covers global consumption, production, and trade dynamics of container glass from 2027 to 2033. Analytical limitations include regional variances in informal recycling data and proprietary confidential furnace capacity disclosures from privately held regional manufacturers.
Recent Industry Developments and Strategic Moves
Recent milestones in the Container Glass Market feature strategic acquisitions and furnace electrification partnerships by firms like Bormioli Rocco and Piramal Glass Private Limited. These initiatives aim to drastically reduce Scope 1 carbon emissions while expanding custom manufacturing capabilities for global brand owners.